
Belly cargo accounted for more than half of every tonne of air freight carried in 2025, moving in the belly of a passenger aircraft. That single figure captures both the remarkable growth of air cargo demand and a structural vulnerability that the industry has not yet resolved.
What the IATA Numbers Actually Show
IATA reports that global air cargo demand rose 3.4% year-on-year in 2025, reaching a record volume. The growth was not evenly spread. Asia-Pacific airlines led all regions with 8.4% year-on-year growth, and African airlines recorded 6.0% growth. European carriers grew at 2.9% and Latin American and Caribbean carriers at 2.3%. Middle Eastern carriers, once the fastest-growing freight corridor, managed just 0.3%. North American carriers were the only regional grouping to record a decline, at 1.3% year-on-year.
Yields fell 1.5% year-on-year in 2025, the smallest annual decline in three years. Crucially, IATA notes that yields remain 37.2% above their 2019 levels, which tells us the market is normalising from pandemic highs rather than deteriorating. For 2026, IATA forecasts demand growth moderating to 2.4%.
IATA also identifies a shift in trade lane patterns, with flows on the Asia-North America lane giving way to Asia-Europe, driven by US tariff policy and the removal of the US de minimis exemption for low-value parcels. That structural change in trade routes has direct consequences for which belly capacity is available, and where.
Why Belly Cargo's 56% Share Creates a Supply Problem
The dependence on belly cargo is a function of how the widebody freighter fleet has stalled. The narrowbody cargo market has been oversupplied since 2023, while the widebody market faces a persistent capacity shortage, according to both Air Cargo News and IBA (aviation asset valuation and advisory).
Belly space on widebody passenger aircraft fills the gap, but it is not a substitute that the industry controls directly. It follows passenger route decisions, aircraft utilisation schedules and airline commercial priorities. When passenger networks contract, as they did sharply in 2020 and can do again for any number of reasons, belly capacity vanishes with them. The freight industry then has nowhere near enough dedicated freighter capacity to absorb the shortfall.
The widebody freighter order book offers little near-term relief. Air Cargo News reports that Boeing's 777-8F, the most significant new widebody freighter in development, has had its launch date pushed back from 2027 to 2028 at the earliest. Air Cargo News also reports that widebody freighter manufacturing supply chains remain unstable, and that disruption is expected to continue for several years. We examined the broader pattern of Boeing programme delays in our earlier analysis of the 737 MAX 10 and 777X delay question; the 777-8F fits the same pattern.
IBA (aviation asset valuation and advisory) notes that the final Boeing 777-300ER left the production line in April 2022. That aircraft is widely converted to freighter configuration, and its exit from production tightens the pipeline of future conversion candidates.
The Age of the Fleet and What It Means
The dedicated freighter fleet is ageing. Air Cargo News reports that the average age of the cargo fleet is significantly higher than that of the passenger fleet, and that the gap between the two is widening. An older fleet means higher maintenance costs, greater exposure to airworthiness directives, and the risk of aircraft leaving service faster than replacements arrive.
One conversion programme that has attracted attention is the Mammoth Freighters 777-200LRMF. Air Cargo News and IBA both report that Mammoth completed the initial test flight of its 777-200LRMF prototype in May 2025, but that the programme has faced a lengthy wait for its supplemental type certificate. Until that certificate is granted, the aircraft cannot enter commercial service, and the widebody capacity gap remains unaddressed by that programme.
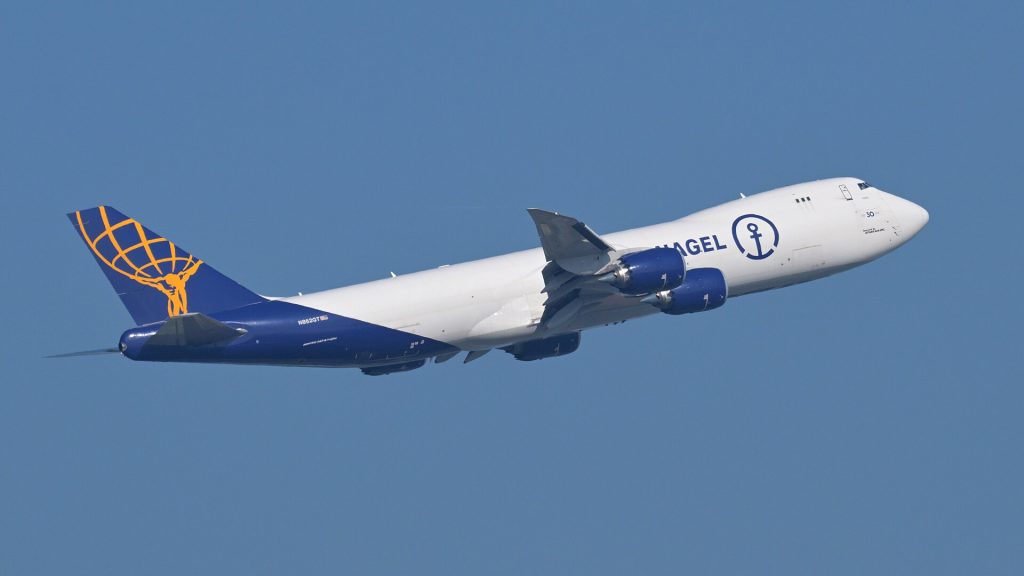
At the premium end of the widebody market, demand for specific types is rising sharply. IBA (aviation asset valuation and advisory) reports that AI-related and semiconductor shipments are driving demand for 747-400F and 747-8F aircraft, specifically because of their nose-loading capability, which allows outsized cargo to be carried that cannot fit through a standard side cargo door. That demand concentration in ageing 747 variants underlines how thin the supply of suitable widebody freighters has become. You can explore freighter types and their operators using our Aircraft Search.
The North America Signal Worth Watching
The 1.3% demand decline recorded by North American carriers in 2025 deserves attention beyond its regional significance. It is the only outright decline in the global picture, and it coincides directly with the trade policy shifts that IATA identifies as redirecting cargo away from Asia-North America lanes. If those policy conditions persist or intensify, North American belly capacity on transpacific routes will be partly underutilised for freight purposes even as the widebody freighter fleet remains short globally. The mismatch between where belly capacity sits and where freight demand is growing is a structural issue, not a temporary one.
The Bottom Line
The 56% belly cargo share is not a sign of a healthy, diversified air freight market. It is the result of a dedicated freighter fleet that has not kept pace with demand, a widebody manufacturing pipeline that is running years behind schedule, and a conversion market that is working through regulatory and supply-chain delays. IATA's record 2025 demand figure and yields that remain 37.2% above 2019 levels confirm that the commercial case for more capacity is as strong as it has ever been. The gap between that case and the industry's ability to deliver new lift is what makes the current reliance on belly cargo a structural risk rather than a strategic choice.
If passenger networks were to shrink, whether from an economic shock, a geopolitical disruption or a sharp shift in consumer demand, the belly cargo share that now underpins more than half of global air freight lift would contract with them, and there is no standby freighter fleet large enough to absorb it.
This article draws on information from IATA and reporting by Air Cargo News and IBA (aviation asset valuation and advisory).
Continue to follow The Aviation Hub for more analysis and insight.
Advertise with us Your brand, in front of an aviation audience Home page and in-article placements, sold directly, one advertiser per slot. From £250 a year. See the rates