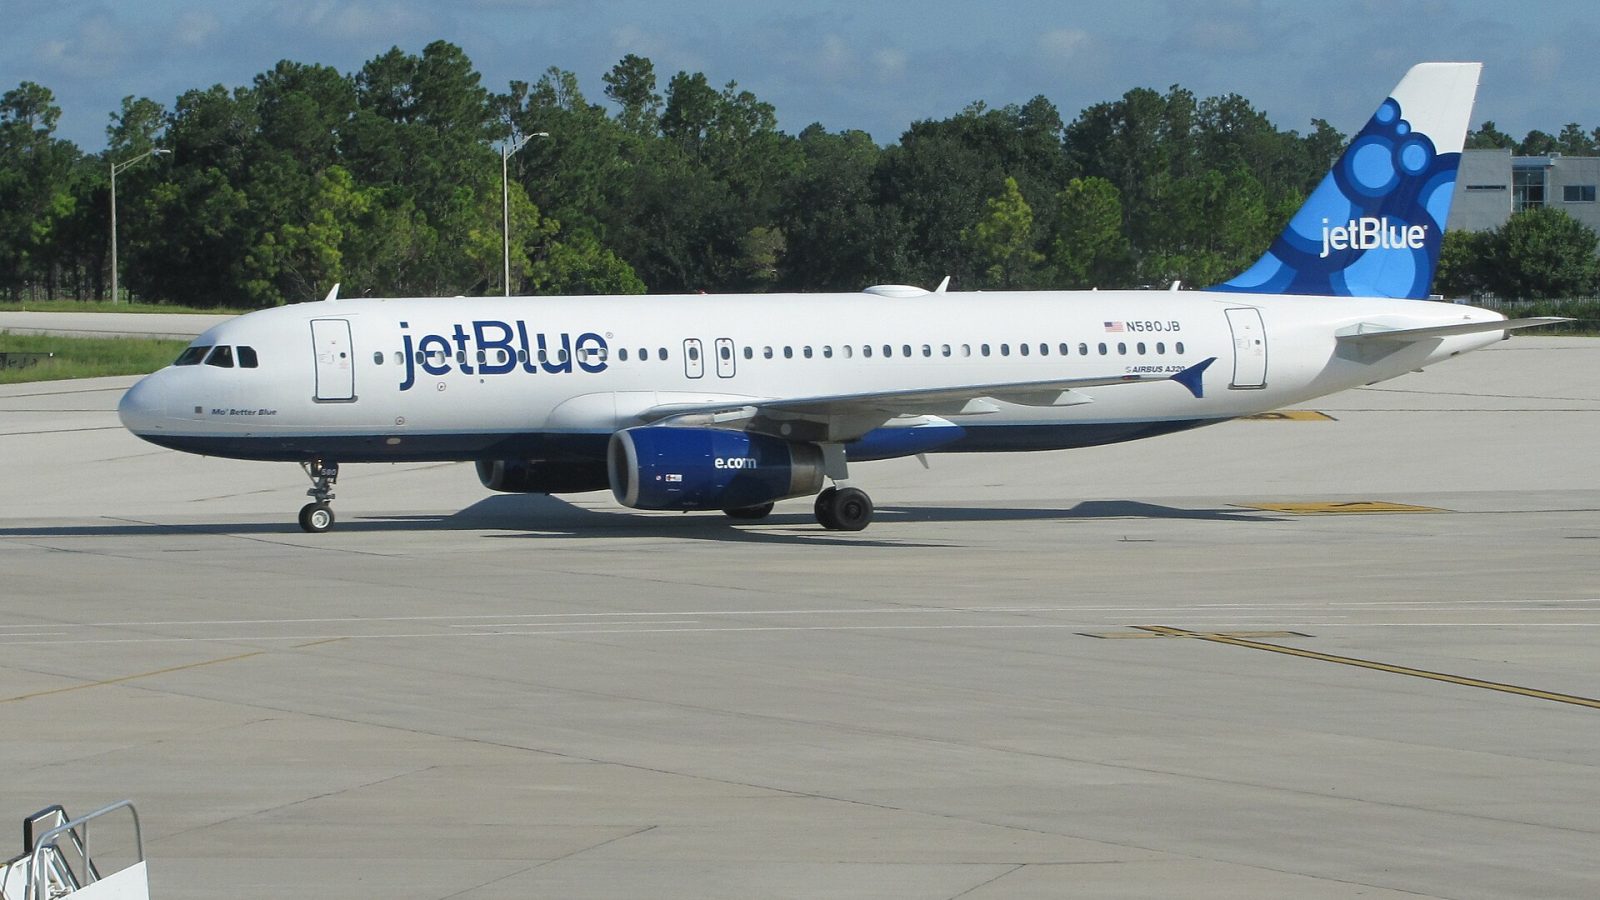
JetBlue released its third-quarter 2026 financial results on 26 October, reporting a net loss of US$257m as a dramatic rise in fuel costs consumed the gains from one of the carrier's stronger revenue quarters in recent memory. The headline numbers make uncomfortable reading even against a backdrop of genuine commercial progress.
Readers tracking JetBlue's recovery can find a full profile of the airline's network and fleet through our Airline Search tool.
Revenue Recovery That Was Not Enough
According to Airways Magazine, revenue climbed 21.1% year over year to US$2.812bn in the quarter, with the average fare rising 19.2% to US$245.11. Capacity grew a modest 2.3%, meaning the fare improvement was largely driven by pricing rather than seats added.
Load factor slipped 1.5 percentage points to 83.6%, a sign that the higher fares did thin demand at the margin. Operating revenue came in at 16.28 cents per available seat mile, a solid unit revenue figure that would have looked healthy in a lower-cost environment.
Within the network, Fort Lauderdale was a clear bright spot. Unit revenue at the airport climbed nearly 15% in the third quarter, and that gain came even as capacity there grew by more than 65%, pointing to robust underlying demand at JetBlue's Florida hub, as Airways Magazine reports. Over the coming winter, Fort Lauderdale is set to support a peak schedule of over 150 daily departures.
The Fuel Bill That Changed Everything
The problem was not on the revenue side. Fuel expense rose 61% to US$868m, a figure that single-handedly explains why stronger ticket sales failed to produce a profit. Operating expenses in total increased 22.1% to US$2.956bn, outpacing revenue growth and leaving an operating loss of US$144m compared with US$100m in the same quarter a year earlier.
Airways Magazine notes that the cost per available seat mile came in at 17.12 cents while operating revenue stood at 16.28 cents per seat, meaning the airline was outspending its earnings before anything below the operating line is considered. The net loss deepened to US$257m compared with US$143m in the same period a year earlier, and the diluted loss per share moved from US$0.39 to US$0.68.
Not every metric pointed downward, however. The adjusted operating margin edged in a more favourable direction, improving to negative 3.9% from negative 4.1% in the prior year period, a modest shift that reflects the airline's gathering revenue momentum even if the absolute position remains deeply uncomfortable.
JetBlue's Full-Year Outlook Revised Downward
The fuel picture has worsened since JetBlue last updated its guidance. The airline has raised its annual fuel cost assumption to US$3.95 per gallon from US$3.49 in July, according to Airways Magazine. For the fourth quarter specifically, the assumption sits at US$4.64 per gallon, based on forward curves as of 16 October.
That revision feeds directly into the full-year adjusted operating margin forecast, which has been moved to a range of negative 6.5% to negative 4.5%, compared with the previous guidance of negative 5% to negative 2%. The direction of travel is clear: fuel has overtaken commercial recovery as the dominant variable in JetBlue's near-term finances.
On the more encouraging side, fourth-quarter unit revenue is expected to rise between 18% and 22% year over year, suggesting the pricing momentum seen in Q3 is carrying into the final months of the year.
Liquidity and the Balance Sheet
As of the end of September, JetBlue held roughly US$1.63bn in cash and investment securities, and Airways Magazine reports that total stated liquidity reaches US$2.2bn once a US$600m undrawn credit facility is brought into the calculation. Given the ongoing scale of losses, that financial cushion carries considerable importance.
The 2028 earnings-per-share target of at least US$1.00 was set with fuel assumed at US$3.00 per gallon. With the current annual assumption nearly a dollar per gallon higher than that, the path to that target has grown considerably more demanding. JetBlue's stated aim is to reach sustained operating profitability in 2027.
BlueFirst: A New Revenue Stream on the Horizon
BlueFirst, the airline's forthcoming premium cabin product, is one development that could meaningfully shift the revenue picture in the quarters ahead. Airways Magazine reports that the product became available to book on 15 October, covering more than 30 routes, and that the inaugural revenue service is scheduled for 8 December, operating between Boston Logan (BOS) and Fort Lauderdale (FLL).
Premium domestic and leisure travel has proved resilient for other carriers, and BlueFirst represents JetBlue's clearest bet on capturing a higher-yielding passenger segment. Whether it moves the needle on unit revenue in a meaningful way will be one of the key questions heading into 2027.
The Bottom Line
JetBlue's Q3 2026 results present a study in competing forces. Revenue growth of more than 21%, fare increases close to 20% and standout performance at Fort Lauderdale all point to a commercial operation that is gaining traction. Against that, a 61% rise in fuel costs has overwhelmed those gains and pushed the full-year margin outlook deeper into negative territory.
The revised fuel assumptions and the widened net loss will concern investors focused on the 2027 profitability target. The quarterly results, in isolation, do not demonstrate that the target is within reach, though the unit revenue trajectory and the BlueFirst launch give JetBlue something constructive to point to as the year closes. The fourth quarter will be worth watching closely.
Continue to follow The Aviation Hub for more analysis and insight.
Advertise with us Your brand, in front of an aviation audience Home page and in-article placements, sold directly, one advertiser per slot. From £250 a year. See the rates