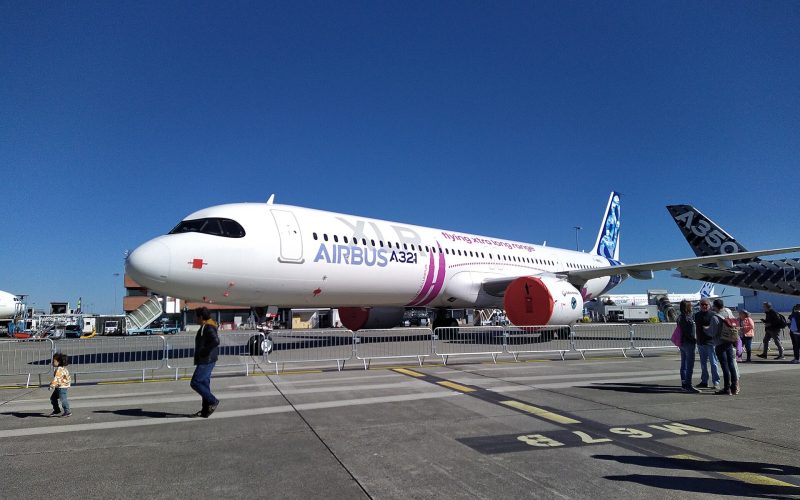
What the numbers around SAF reveal most starkly is not the scale of current output, but the distance between what is being made and what could be made. According to IATA, global SAF production is on course to hit approximately 2.4 million tonnes in 2026, a figure that appears significant in isolation yet looks far more modest when measured against the existing capacity that sits idle or underused.

The SAF Production Capacity That Goes Unused
If the industry's installed capacity could be converted directly into output, 2026 would look very different. Instead, IATA puts 2.4 million tonnes at just 0.8 per cent of total aviation fuel use this year. SAF will cost airlines $4.3 billion in 2026, according to IATA, yet even at that price and that cost, facilities are running nowhere near full output.
Nowhere is the gap more acute than in e-SAF, the very segment that regulators have leaned on most heavily. IATA puts total e-SAF capacity, both operational and under construction worldwide, at approximately 0.02 million tonnes, with just a single facility currently producing anywhere on the planet. Over the past twelve months, IATA records that not one new final investment decision for an e-SAF plant has been committed to. That is not a slow-moving pipeline; it is one that has scarcely got off the ground.
EASA has published the ReFuelEU Aviation Annual Technical Report 2026, drawing on 2025 data. That year was the first in which the core obligations of the ReFuelEU Aviation Regulation came into force. A corrigendum issued on 02/11/2026 amended the report to clarify figures relating to SAF production and import statistics, though it explicitly does not affect the report's findings on volumes of SAF supplied at Union airports in 2025 or any other KPI included in the report.
What Mandates Require and What Exists to Meet Them
The targets set by regulators are not modest. The EU and UK together have set an e-SAF production mandate of approximately 0.6 million tonnes by 2030, as cited by IATA, which also calculates that meeting that volume would require roughly 20 commercial-scale refineries to be built and running. Against a backdrop of one operational site and a year in which no fresh investment commitments were made, according to IATA, the numbers tell a difficult story.
On conventional renewable fuels, the United States offers a different picture, though the distinction between fuel types is important to keep in mind. By the close of 2026, 23 renewable diesel plants will be operating across the US, according to farmdoc daily (University of Illinois). US renewable diesel production capacity is estimated to reach 5.3 billion gallons in 2025, farmdoc daily (University of Illinois) reports, with total capacity projected to remain static through 2026 at 5.261 billion gallons. Renewable diesel and SAF are closely related but not interchangeable, since not every barrel of renewable diesel feedstock ends up as jet fuel. Farmdoc daily (University of Illinois) also records that, back in 2021, the Biden Administration set a goal of 3 billion gallons of US SAF output by 2030. The distance between that ambition and the current state of e-SAF investment suggests that policy intent has not yet drawn committed capital into the sector.
The 2050 Target and the Distance Still to Travel
The aviation industry committed to net zero by 2050 five years ago, according to IATA, and SAF is targeted to meet 65 per cent of aviation's fuel needs by that date, IATA states. Moving from 0.8 per cent of fuel use today to 65 per cent in 24 years is a trajectory that requires investment decisions to be made now, given the lead times involved in building commercial-scale facilities. The absence of new e-SAF final investment decisions in the past year is therefore not a minor data point; it is the central problem the industry faces.
This connects directly to our earlier analysis of how rising costs are already feeding through to ticket prices. SAF alone is adding $4.3 billion to airline cost bases in 2026, and survey data from IATA indicates that nearly 88 per cent of passengers anticipate fares climbing as a result of sustainability investments. Should mandated volumes rise and cost burdens follow, the commercial strain on carriers will only deepen. Our Airline Search tool offers a useful starting point for anyone wanting to understand which airlines face the greatest exposure to those pressures.
What Passengers Say They Want
It is worth looking at the demand side with clear eyes. In an April 2026 survey conducted by IATA, 89 per cent of passengers took the view that the industry ought to continue cutting emissions regardless of whether governments maintain their current level of effort. IATA also found that 48 per cent of travellers consult carbon emissions data as part of their flight selection process, and among that group, more than 85 per cent report that it has a bearing on which flight they ultimately book.
Where the apparent consensus begins to fracture is on the question of who should foot the bill. According to IATA, 66 per cent of passengers indicate a readiness to contribute financially to offset their emissions. When it comes to how those sustainability funds should be allocated, IATA data shows 25 per cent of passengers would direct the money towards SAF, 23 per cent towards emissions-reduction technologies, and 10 per cent towards taxes. As the industry knows well, a stated willingness to pay and actual spending behaviour are often quite different things, and bridging that gap remains an enduring challenge.
The Bottom Line
The core problem is not that the world lacks the physical infrastructure to produce more SAF. It is that investment in new e-SAF capacity has stalled at precisely the moment when regulatory deadlines are drawing close enough to matter. With one operational e-SAF site globally, no new final investment decisions in the past year, and a mandate requiring around 20 commercial-scale refineries by 2030, the EU and UK targets look very difficult to meet on current trajectories.
For passengers, the practical consequence is that SAF costs will continue to push up fares while the fuel itself remains a marginal share of what goes into the tank. IATA figures show the industry has been transparent about the cost: $4.3 billion in 2026 for 0.8 per cent of fuel needs. The question that the next twelve months will answer is whether the absence of investment decisions becomes a pattern or a pause.
This article draws on information from IATA and EASA (European Union Aviation Safety Agency) and reporting by farmdoc daily (University of Illinois).
Continue to follow The Aviation Hub for more analysis and insight.
Advertise with us Your brand, in front of an aviation audience Home page and in-article placements, sold directly, one advertiser per slot. From £250 a year. See the rates