
The supply chain crisis cost airlines over $11bn in 2025, according to IATA and industry figures reported by Air Cargo News and STAT Times. That single-year figure sits inside a widebody freighter capacity problem that, by most measures, will not resolve itself until well into the next decade.
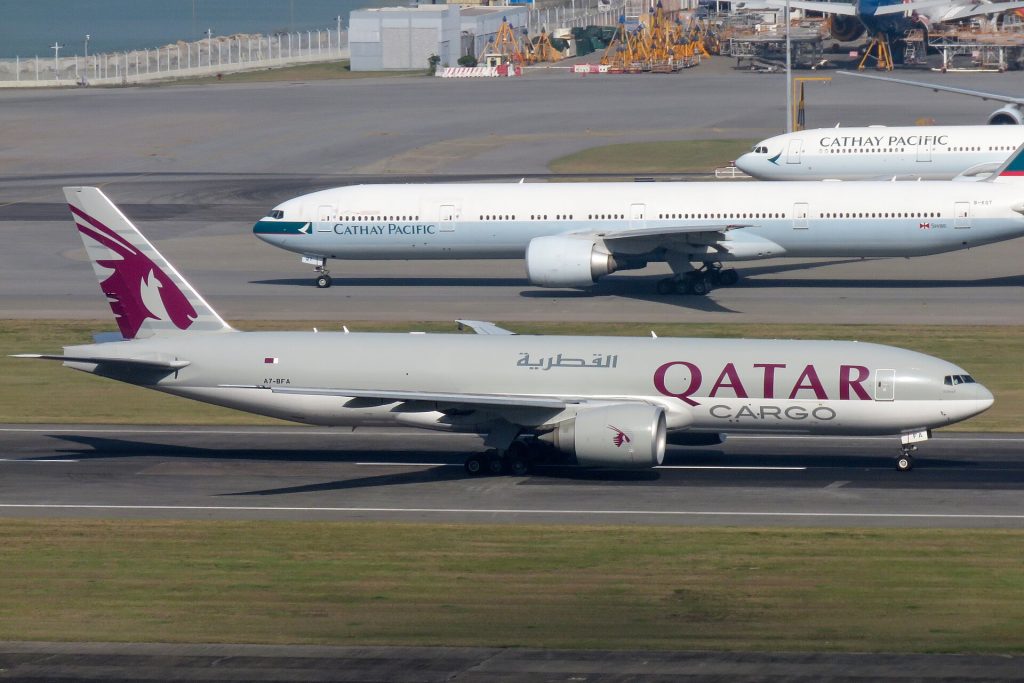
The gap has three dimensions: not enough new aircraft coming off the production line, an ageing in-service fleet being kept flying beyond its natural service life, and a backlog so large it dwarfs annual delivery rates. Each dimension compounds the others.
A Widebody Freighter Backlog Eleven Times Annual Output
The global aircraft order backlog now exceeds 17,000 units, close to 60% of the entire active fleet, according to Air Cargo News and STAT Times. That number alone does not capture the severity of the position. What matters is the relationship between orders outstanding and the rate at which manufacturers can clear them. Air Cargo News reports that the backlog is eleven times the number of aircraft delivered each year.
By the close of 2025, global aircraft production stood around 24% below 2019 levels, STAT Times reports, with the cumulative shortfall across the industry reaching approximately 6,000 aircraft, STAT Times also reports. The knock-on effect for fleet growth is stark: projected expansion through 2036 now trails what had been expected before the pandemic by six years, STAT Times reports.
Air Cargo News reports that net cargo aircraft added to the fleet fell in both 2024 and 2025, meaning the freighter fleet actually shrank in net terms across consecutive years. Julia Seiermann, IATA's head of industry analysis, frames the timeline plainly: "What this means is that even under the expectation that production and deliveries will accelerate in 2026, which is now the view of analysts, normalisation is unlikely to occur before the early 2030s."
Aircraft Kept Flying Long Past Their Prime
While new jets queue in backlogs, the ones already flying are accumulating age rapidly. IBA (aviation asset intelligence) reports that the average retirement age of 777 and A330 family aircraft reached roughly 22 years by 2025 and 2026. To put that in context, IBA reports that retirements of those same types peaked at over 60 aircraft in 2021 as Covid-19 hammered passenger demand. Many of the aircraft that survived that cull are now being stretched further still.
The financial burden of keeping ageing widebodies airborne is considerable. According to Air Cargo News and STAT Times, airlines absorbed an extra $4.2bn in fuel costs in 2025 owing to older, less efficient aircraft, while maintenance expenditure rose by a further $3.1bn and spare-parts stockpiling added $1.4bn on top of that. A $2.6bn increase in engine leasing costs in 2025 compounded the picture further, Air Cargo News and STAT Times report.
Seiermann put the structural risk plainly: "At some point, this strategy will reach its limits when aircraft will need to be retired, and then shortages may become even more pronounced."
What Operators Are Already Feeling
Behind the headline figures lies an operational challenge that those responsible for capacity planning understand acutely. Atlas Air Worldwide's chief commercial officer and head of sustainability, Richard Broekman, put it plainly to STAT Times: "We know there's going to be a tremendous shortage of widebody freighter capacity." He continued: "The biggest challenge for us is indeed access to additional capacity."
For cargo carriers, that means competing for a finite pool of ageing widebodies, paying elevated lease and engine costs, and accepting fuel burn and maintenance bills that would not exist with newer equipment. The costs flow downstream. Shippers pay more, and those costs eventually reach consumers.
The aircraft at the centre of the replacement question are the Boeing 777-8F and the Airbus A350F, both of which we have covered in depth. Both are delayed. That delay is a core reason why operators cannot retire older jets on a commercially rational timeline, and why the numbers above look the way they do.
What $11bn Actually Breaks Down To
The IATA figure of over $11bn in supply chain costs for 2025 is not a single cost but a composite. Fuel inefficiency accounts for $4.2bn of it, maintenance for $3.1bn, engine leasing for $2.6bn and spare-parts stockpiling for $1.4bn, according to Air Cargo News and STAT Times. Added together those four components total $11.3bn, a figure that maps closely to the IATA headline estimate.
Each of those lines reflects a workaround, not a solution. Excess fuel burn is what happens when a 22-year-old widebody flies a route a new-generation freighter would fly more efficiently. Higher maintenance costs are what happens when retirement is deferred. Engine leasing premiums are what happens when demand for serviceable powerplants outstrips supply. Spare-parts stockpiling is what happens when operators lose confidence in just-in-time supply chains. The costs are the financial expression of a fleet renewal programme running years behind schedule.
We previously noted that Cirium has lowered its aircraft delivery forecast to 43,000 through 2045, which is consistent with the picture IATA and industry executives are describing here. Fewer deliveries over a longer horizon means the gap persists longer.
Readers wanting to explore the freighter types at the centre of this debate can use our Aircraft Search to look up specifications, operators and fleet data for the 777F, A350F and their predecessors.
The Bottom Line
The widebody freighter capacity gap is real, measurable and expensive. A backlog eleven times annual production, a fleet averaging 22 years of age, and costs of over $11bn in a single year are not projections: they are what 2025 actually looked like. Air Cargo News reports that normalisation of aircraft supply is unlikely before the early 2030s, a timeline that IATA's own analysis supports. Until new-generation freighters arrive in meaningful numbers, airlines and cargo operators will keep paying the premium for keeping old jets flying. That premium, spread across the global supply chain, is ultimately a cost that reaches far beyond the aviation industry.
This article draws on reporting by Air Cargo News, STAT Times and IBA (aviation asset intelligence).
Continue to follow The Aviation Hub for more analysis and insight.
Advertise with us Your brand, in front of an aviation audience Home page and in-article placements, sold directly, one advertiser per slot. From £250 a year. See the rates